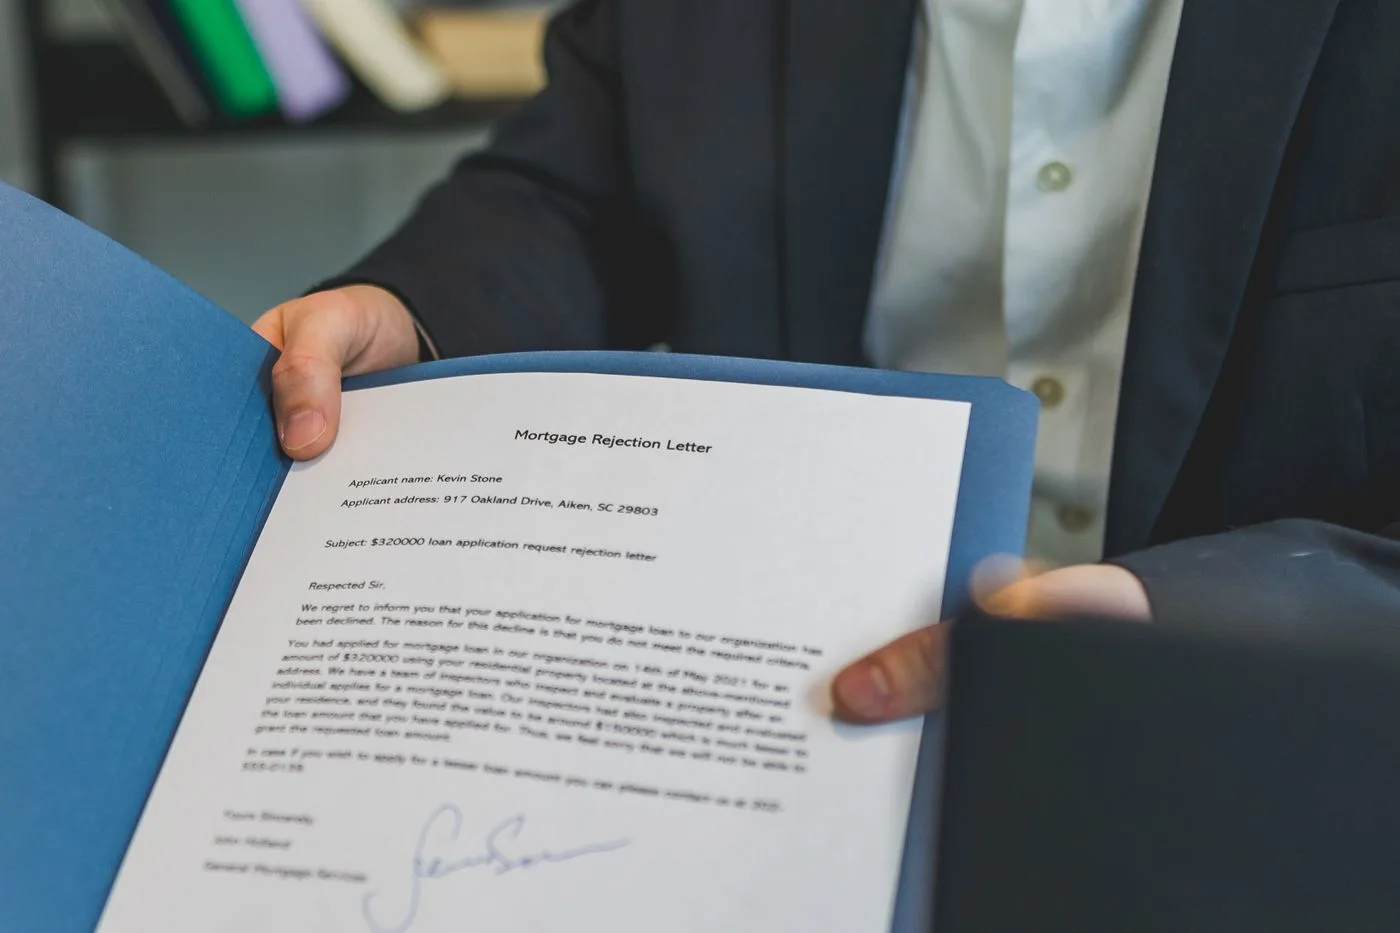
A declined application can feel like a single verdict, but the accompanying notice contains several different pieces of information. Read it as a record of a particular decision, made by a particular company using information available at that time. It can help you identify an error or understand what to investigate before another application.
Find the decision and its reasons
Locate the creditor's name, the application reference and the date. Then find the specific reasons for the decision or the instructions for requesting them. Do not confuse a general promotional statement with the actual reason section.
The CFPB explains adverse action notices, including the right to reasons and the additional information required when credit-report information was involved. Read the notice's deadlines promptly instead of filing it away until the next time you need credit.
Create a short note for each reason. “Unable to verify income” calls for a different investigation from “high debt relative to income.” One concerns evidence; the other may concern the underlying financial position. Neither is automatically fixed by applying again with the same information.
Separate score factors from lending reasons
If a credit score was used, the notice may identify the score and factors affecting it. Those score factors are not necessarily the full list of reasons the creditor declined the application. A lender can evaluate income, obligations and product requirements in addition to the score.
For example, a hypothetical notice could mention a short credit history among score factors while the credit decision also cites insufficient verified income. Focusing only on adding another credit account would overlook the income issue and create another application without addressing it.
Keep the exact wording in your notes. Replacing a precise reason with “bad credit” can make your next steps less useful.
Obtain the report identified in the notice
When the decision was based on a credit report, the notice should identify the reporting company and explain the right to request a free report within 60 days. Request the relevant report and save the notice together with it. Do not assume that a score-monitoring app shows the same underlying file used by the creditor.
Compare account ownership, balances, payment status and inquiries with your records. If a balance differs, check its reporting date. If an account is not yours, do not dismiss it as a routine update delay.
For a question about the lender's income calculation, gather the application and supporting pay records. A credit bureau cannot correct a number that exists only in the lender's application system.
Match the response to the problem
For inaccurate report information, use the dispute process with the reporting company and the business that supplied the information. For missing documents, ask the lender what was missing and whether the application can be reconsidered or requires a new submission. Reconsideration is not guaranteed.
If the information is accurate, consider whether the requested amount, timing or product still makes sense. A denial is not a reason to accept the first alternative regardless of cost. Compare the full repayment obligation and whether the original expense can be reduced or delayed.
Do not pay a company promising to remove accurate negative information or guarantee approval. A factual correction and a promise to change a lending outcome are different things.
Ask a focused follow-up question
When contacting the lender, identify the application and quote the relevant reason. A useful question is, “Which income document could not be verified, and what information was missing?” That invites a more specific response than asking why the lender does not like your credit. Record whether the answer concerns a factual error, an incomplete file or a lending policy.
If someone offers to reconsider, ask whether the existing application can be reviewed, what new information is needed and whether another credit inquiry will occur. Do not submit several replacement applications simply because a telephone representative suggested trying again. Clarify the process and retain the response.
Keep expectations proportionate. Correcting one item can resolve that issue without removing every other reason for the decision. Conversely, a lender saying it cannot change the outcome does not establish that incorrect report information should remain unchallenged. Accuracy matters beyond this one application, including later borrowing and your own understanding of the record.
Keep the case organized
Record when you requested reasons, obtained the report, submitted evidence and received a response. Preserve confirmation numbers and copies of letters. If a response does not address your specific issue, refer back to the exact field or decision reason that remains unresolved.
If you believe the decision involved unlawful discrimination, preserve the application and communications and consult the relevant consumer-protection resources. The CFPB's credit-discrimination page describes protected characteristics and complaint options.
Before applying elsewhere, write down what has changed since the declined application. A corrected record, a documented income source or a smaller genuine borrowing need is concrete. An expectation that another form will somehow produce a different answer is not a plan.